Getting the balance right between income, growth and capital preservation as investment horizons widen.
Key points
Listed investment companies (LICs) have been an enduring feature of Australia’s sharemarket for more than a century.
An LIC is a company that invests shareholders’ pooled capital in a portfolio of assets, often shares. Like any other listed company, an LIC’s shares are bought and sold on ASX, potentially giving investors access to a diversified, actively managed portfolio with a small minimum investment.
(More information on the features, benefits and risks of LICs is available here).
However, not all LICs are alike, and investors need to understand these differences as they may have a bearing on their returns.
In this article, Argo outlines five key factors to consider before investing in an LIC:
The first factor is whether the LIC is internally or externally managed.
Many of Australia’s largest and oldest LICs, such as Australian Foundation Investment Company (ASX: AFI) and Argo Investments (ASX: ARG), are internally managed. These LICs employ their own in-house investment and management teams and therefore operate as both the manager and the investment vehicle.
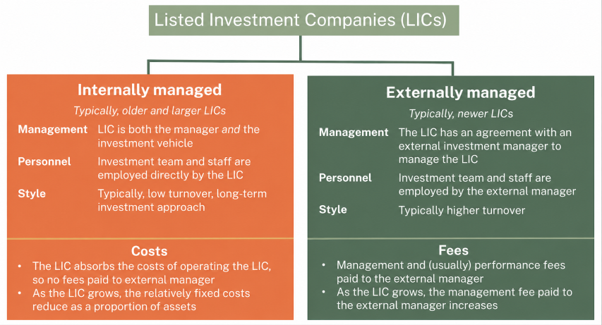
Externally managed LICs, which have made up most of those listed since the early 2000s, are managed by an external fund manager under a management agreement.
The main differences are outlined below.
Source: Argo Investments
The distinction between the two may be relevant when considering alignment of interests, fees or costs, investment behaviour and shareholder returns over time.
Another distinction between internally and externally managed LICs is their fee structure.
Internally managed LICs
For an internally managed LIC, all operating costs (wages and administrative costs such as rent, regulatory costs, research tools and brokerage) are captured within the management expense ratio (MER). The MER is expressed as a percentage of the LIC’s assets and is accounted for in the reported net tangible asset (NTA) performance.
As the internally managed LIC grows, its relatively fixed operating costs tend to reduce as a proportion of assets.
For large, long-established LICs, the MER is usually between 0.1% and 0.2%. (The ASX Investment Products monthly report shows the MER for every LIC on the ASX).
Externally managed LICs
In addition to its own administration costs, an externally managed LIC also pays a management fee to its external manager, based on a percentage of the LIC’s assets. The management fee is often between 0.7% and 1.0%, sometimes as high as 2.0%, depending on the investment strategy, based on Argo’s analysis. As the LIC’s assets grow, the management fee increases.
These LICs will often pay a performance fee on top of the management fee, typically between 10% and 20% of returns above the LIC’s benchmark or hurdle [against which their portfolio’s investment performance is compared].
Fee structures differ and may create different incentives for external managers, such as more active investment strategies with higher turnover or that are focused on short-term performance[WH5.1]. For LICs with high portfolio turnover, brokerage expenses and tax liabilities may be considerable, potentially eroding capital over time (see point 3, Dividend Sustainability, below).
Investors may be attracted to some externally managed LICs because they offer access to specialised strategies, managers or less accessible asset classes, like international markets, private equity, or private debt, with a small minimum investment via ASX.
In Argo’s opinion, it is important to understand whether an LIC’s reported portfolio performance is calculated before or after fees.
For an externally managed LIC, NTA performance returns can be markedly lower than portfolio performance returns after management, performance and administration fees are deducted.
Note: Purchasing, selling, or holding LICs involves no direct fees for investors, aside from brokerage costs. The expenses associated with managing an LIC are deducted from its assets and income.
An LIC typically generates income in two main ways: dividends received from its underlying portfolio and from realising capital gains. It can then pay this income to shareholders as dividends.
An important and distinguishing feature of LICs, particularly compared to exchange-traded funds (ETFs) and other investments using a trust structure, is their ability to accumulate earnings from multiple periods in retained earnings or a profit reserve.
LICs may then use those reserves to distribute dividends during weaker years, which may reduce variation in dividend payments between periods; however, future dividends are not guaranteed.
Although an LIC’s future dividend cannot be guaranteed, its capacity to maintain or grow its dividend can be assessed by looking at several factors, including the LIC’s dividend record and the retained earnings or profit reserve in its financial accounts.
LICs may sell assets from their portfolios to fund dividend payments to shareholders. They may do this to maintain a higher level of dividends or to distribute excess franking credits.
Over time, this practice may reduce the LIC’s capital base, from which it derives dividends and generates gains. This can restrict potential future dividends to shareholders.
Because an LIC is an Australian corporate taxpayer, when it realises gains on investments in its portfolio and pays corporate tax, it generates imputation (franking) credits, even on overseas assets.
Additionally, an LIC can receive franking credits on dividends from its investment portfolio if those investments pay Australian corporate tax.
These credits accumulate in a franking account and are distributed with dividends,
Investors can refer to an LIC’s Annual Report for its franking account and LIC capital gain account. If the franking balance is insufficient or trending lower over time, the LIC may not be able to fully frank its future dividends.
Because an LIC is a closed-end structure, buyers and sellers on the ASX set its share price, which can trade above (a premium) or below (a discount) its NTA[WH7.1] per share.
Some investors see these discounts as an opportunity to buy the underlying assets below market price, hoping the shares will trade closer to the NTA in time.
A range of factors can influence premiums and discounts, some specific to the LIC such as portfolio performance and dividend track record, as well as external factors, such as the interest rate environment and market trends.
Smaller or less liquid LICs may trade at wider discounts, although this varies across products and market conditions.
No single factor will determine if an LIC is a worthy investment. However, taken together, these five factors provide a more fulsome picture of the key features and risks of LICs.
Listed Investment Companies and Listed Investment Trusts has information on the features, benefits and risks of LICs and LITs, and is a good place to start for investors who are new to this market and want more information.
About the authors
DISCLAIMER
The views, opinions or recommendations of the author in this article are solely those of the author and do not in any way reflect the views, opinions, recommendations, of ASX Limited ABN 98 008 624 691 and its related bodies corporate (“ASX”). ASX makes no representation or warranty with respect to the accuracy, completeness or currency of the content. The content is for educational purposes only and does not constitute financial advice. Independent advice should be obtained from an Australian financial services licensee before making investment decisions. To the extent permitted by law, ASX excludes all liability for any loss or damage arising in any way including by way of negligence.
This article has been prepared by Argo Service Company Pty Ltd (ASCO) (ACN 603 367 479) (Australian Financial Services Licence 470477), on behalf of Argo Investments Limited (ACN 007 519 520).
ASCO’s Financial Services Guide is available on request or at argoinvestments.com.au.
This article contains unsolicited general information only, which does not take into account the particular objectives, financial situation or needs of any individual investor. It is not intended to be relied upon as a recommendation by any person.
Before making any decision about the information provided, an investor should consult their independent adviser and consider the appropriateness of the information, having regard to their objectives, financial situation and needs.
Past performance may not be indicative of future performance and no guarantee of future returns is implied or given. While all reasonable care has been taken when preparing this article, no responsibility is accepted for any loss, damage, cost or expense resulting directly or indirectly from any error, omission or misrepresentation in the information provided.
Don’t miss the latest insights from ASX Investor Update on LinkedIn
The views, opinions or recommendations of the author in this article are solely those of the author and do not in any way reflect the views, opinions, recommendations, of ASX Limited ABN 98 008 624 691 and its related bodies corporate (“ASX”). ASX makes no representation or warranty with respect to the accuracy, completeness or currency of the content. The content is for educational purposes only and does not constitute financial advice. Independent advice should be obtained from an Australian financial services licensee before making investment decisions. To the extent permitted by law, ASX excludes all liability for any loss or damage arising in any way due to or in connection with the publication of this article, including by way of negligence.