ASX Fixed Income Highlights Q3 – July to September 2026
Futures, Benchmarks, Austraclear and ASX Collateral insights Q3 2026
ASX Fixed Income Highlights Q3 – July to September 2026
Futures, Benchmarks, Austraclear and ASX Collateral insights Q3 2026
Trading activity across ASX 24’s Interest Rate Derivatives grew strongly during the September 2026 quarter, with approximately 59.2 million contracts traded, making it the second-highest quarter across the period against the Q1 2026 peak of 61 million contracts traded. Activity accelerated significantly in September, when monthly volume reached 29.3 million contracts, supported by elevated positioning ahead of the quarterly bond roll due to heightened uncertainty around the domestic and global interest rate outlook creating strong hedging demands.
At a product level, average daily volume increased year on year by 59.7% in 90-Day Bank Bill Futures, 40.1% in 3-Year Treasury Bond Futures and 11.7% in 10-Year Treasury Bond Futures. September open interest was also higher than a year earlier, increasing by 36.9%, 37.3% and 15.6%, respectively, reflecting sustained positioning and risk-management activity across the Australian rates curve.
The September roll provided further evidence of active position management across the bond futures market. Combined 3-Year and 10-Year calendar-spread volume reached 3.58 million contracts during the September roll, approximately 27% higher than September 2025 and 3% above March 2026. This activity was driven by activity from the 3-Year roll, which rose 12.1% from March 2026 levels. Outright trading represented 49% of combined 3-Year and 10-Year Bond Futures activity through the September roll, up from 44% a year earlier, where outright transactions accounted for more than half of all 3-Year activity. This broader balance between calendar-spread and outright trading aligns with the embedded benefits of delinking, giving participants greater flexibility to transfer positions and manage outright exposures independently during the roll period.
During Q3 2026, average daily eligible volume in prime bank NCDs remained strong at $3.17 billion. Consistent with this, transaction-based tenor formation remained robust, averaging 3.6 tenors per day, demonstrating continued depth and liquidity in the underlying market.
BBSW rose about 22–30bp across all tenors between July and September 2026. The main cause was the RBA's 25bp hike on 29 September, which took the cash rate to 4.60%. 3M and 6M rose by roughly the full 25bp even though the hike was widely expected, and 6M is still about 52bp above the cash rate. This suggests the market is pricing at least one further 25bp increase.
The Secured Overnight Funding Index of Australia (SOFIA®) is now live and available through multiple distribution channels such as Bloomberg, LSEG, email and FTP.
SOFIA rose 24.6 basis points to 4.6261% on 30 September 2026, reflecting the Reserve Bank of Australia's 25 basis point increase in the cash rate target to 4.60%.
Since launch, SOFIA has been calculated from an average of 221 eligible transactions and A$16 billion in eligible volume per day.
| Product | Contracts taken to cash settlement (Sep 2026) | % Change (QoQ) |
|---|---|---|
| 90 Day (IR) | 272,740 | 13% |
| 3 Year (YT) | 140,078 | 12% |
| 5 Year (VT) | 819 | 11% |
| 10 Year (XT) | 233,719 | 122% |
| 20 Year (LT) | 601 | 51% |
| NZ 90-Day (BB) | 65,885 | -29% |
ASX OTC Clearing volumes for Q3 2026 were A$2.1 trillion notional value, up 1% vs PCP. Open Interest was A$5.2 trillion, up 6% vs PCP.
During the quarter, banks and clients appeared to take advantage of the lower total cost of clearing available at ASX with an average 60% reduction in Initial Margin requirements, achieved by customers through usage of ASX's fully automated cross-product margin optimisation service.
ASX Collateral continued its strong growth trajectory in Q3 2026, with average balances reaching $33 billion. RBA Open Market Operations (OMO) activity increased to approximately $28.7 billion, with ASX Collateral continuing to facilitate more than half of the activity, reinforcing the platform's important role within Australia's liquidity ecosystem.
Collateral diversification remains a defining trend, with more than one-third of triparty collateral comprising non-government and non-semi-government securities. Line-level analysis also continues to demonstrate strong utilisation of smaller holdings, with sub-$5 million positions forming a significant component of pledged collateral. This highlights the platform's ability to mobilise a broader range of assets, improve collateral efficiency for participants, and unlock value from holdings that may otherwise remain underutilised.
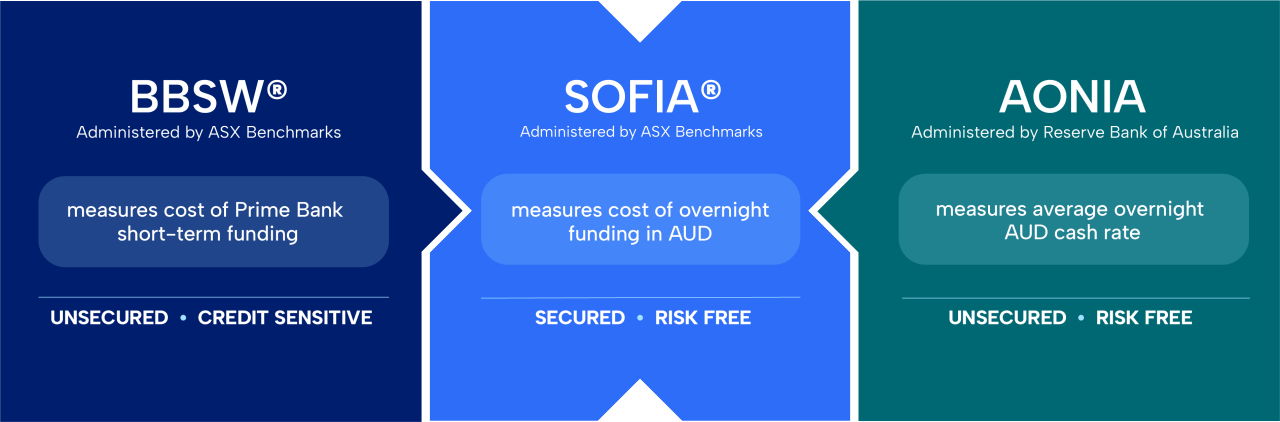
SOFIA provides a new secured overnight reference rate for Australia’s financial markets, based on eligible overnight repo transactions settled through Austraclear®.
SOFIA complements BBSW® and AONIA, expanding Australia’s benchmark toolkit with a secured overnight reference point.
Together, BBSW, SOFIA and AONIA provide market participants with a broader benchmark toolkit across unsecured, secured, credit-sensitive and risk-free markets.
Email: Rates@asx.com.au
asx.com.au/interest-rate-derivatives
Domestic: 131 279
International: +61 2 9338 0000
Disclaimer: Information provided is for educational purposes and does not constitute financial product advice. You should obtain independent advice from an Australian financial services licensee before making any financial decisions. Although ASX Limited ABN 98 008 624 691 and its related bodies corporate (ASX) has made every effort to ensure the accuracy of the information as at the date of publication, ASX does not give any warranty or representation as to the accuracy, reliability or completeness of the information. To the extent permitted by law, ASX and its employees, officers and contractors shall not be liable for any loss or damage arising in any way (including by way of negligence) from or in connection with any information provided or omitted or from anyone acting or refraining to act in reliance on this information.
© Copyright ASX Operations Pty Limited ABN 42 004 523 782. All rights reserved 2026.